Adjuster Coming Thursday? The Paperwork That Decides Your Number
Abstract. An adjuster's license, the scope sheet, the estimate and the proof of loss do most of the work on a claim, and all four can be checked before anyone argues.
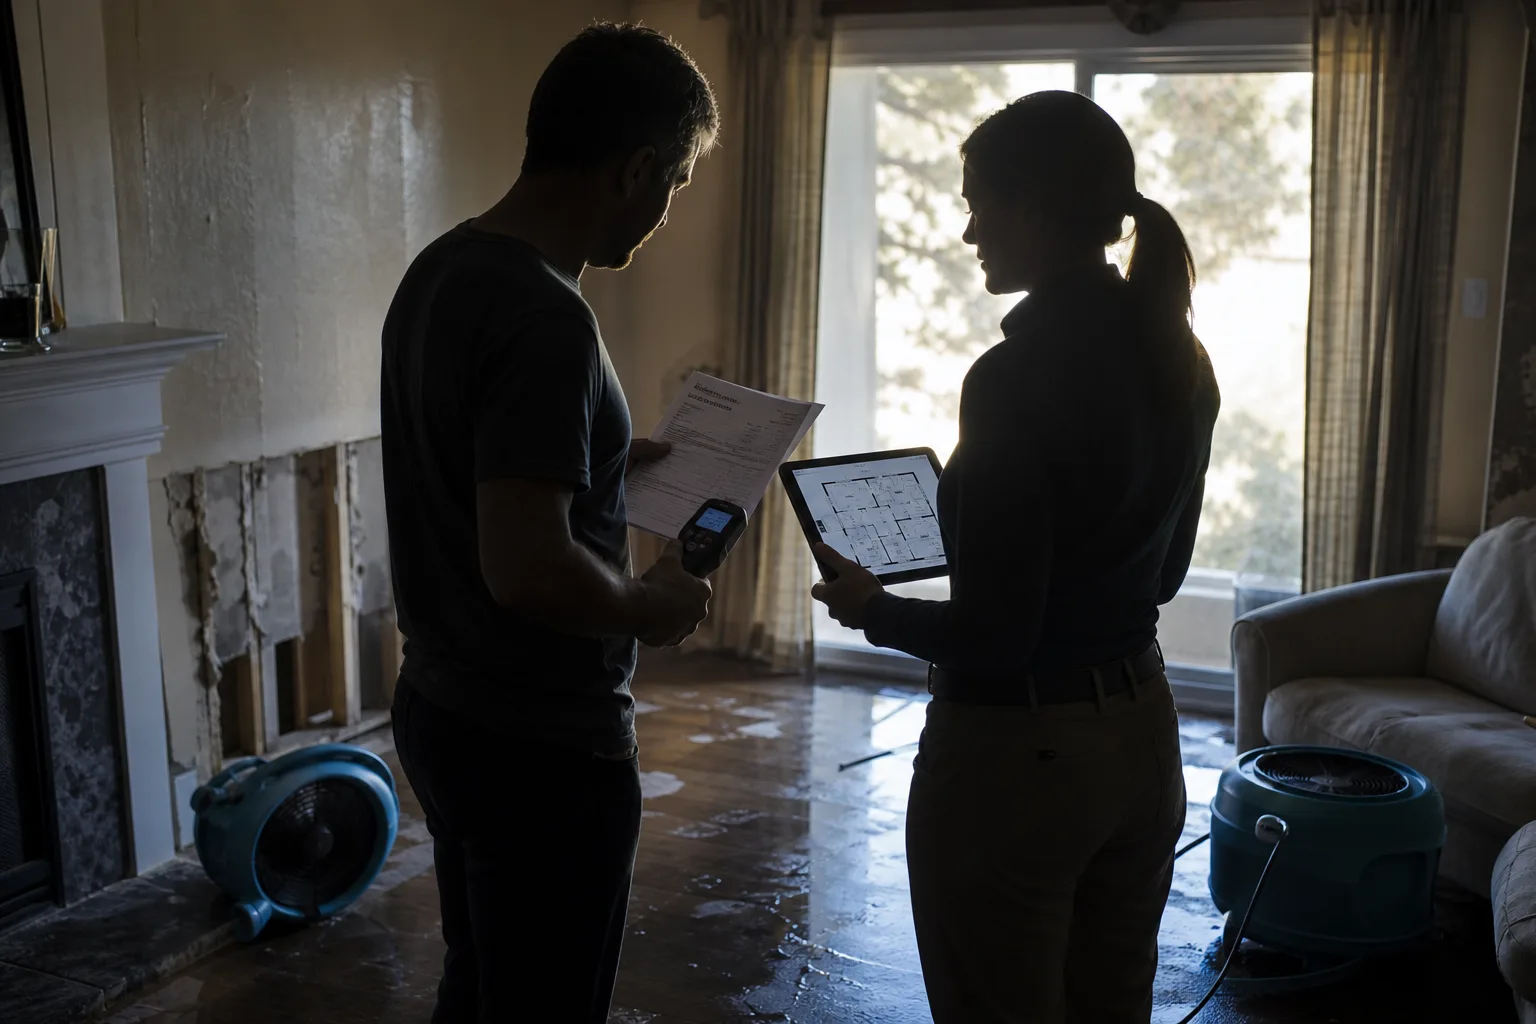
The person who walks through your damaged house with a tablet and a laser measure is not the person who decides your claim, and understanding that distinction early changes how you prepare. An adjuster inspects, scopes and estimates. A file examiner or a supervisor approves. The number that eventually appears on a check is the product of documents, not conversations, and the documents are largely knowable in advance. People who have been through several claims stop trying to win the visit and start building the file, because the file is what travels upward through the carrier while the adjuster moves on to the next assignment.
Three kinds of adjuster, and which one is standing in your kitchen
A staff adjuster is a salaried employee of your insurer, and their loyalty and their paycheck run to the company that issued your policy. An independent adjuster is a contractor hired by that same insurer, common after storms when claim volume spikes, and while they are not on the payroll they are working the carrier's file under the carrier's guidelines. A public adjuster is the only one of the three who can represent you, is paid by you, and owes you the duty. Ask which of the three you are dealing with in the first minute, write down the answer, and note who they said they represent.
The reason to ask plainly is that the answer tells you what the person can and cannot do for you. A staff or independent adjuster can be professional, thorough and fair, and many are, but they cannot advocate for a higher settlement against their own client's interest. That is not a character flaw; it is the structure. Once you know the structure, their scope sheet becomes something you review rather than something you accept, and their estimate becomes a document you compare against a contractor's, which is exactly what it was built to withstand.
What the license actually vets, and where to confirm it
Adjusters are licensed at the state level, not federally, and most states require a resident or nonresident adjuster license with a prelicensing exam, a background check, a fingerprint submission and continuing education on a fixed renewal cycle. The National Association of Insurance Commissioners coordinates the licensing framework that state insurance departments administer, and every state department of insurance maintains a public lookup where you can enter a name or license number and see status, license type, issue date, expiration and any disciplinary action on record. That lookup is the check that matters. It takes about two minutes and it is the only one that is authoritative.
What the license does not vet is competence in your particular loss. A license confirms that someone passed an exam on adjusting practice and has not been sanctioned. It says nothing about whether they have scoped a fire, read a moisture map, or priced a slate roof. That is what designations are for, and a handful are real: the AIC and SCLA administered through The Institutes, the CPCU for broader insurance study, and various restoration credentials on the contractor side. Ask which designation, ask which body issued it, and confirm with the issuing body rather than the business card.
A few states also license public adjusters more heavily than staff adjusters, requiring a surety bond, a filed contract form and a statutory cap on the contingency fee they may charge. If you are hiring one, the bond and the approved contract are the two things to verify before you sign, because they are the consumer protections the state built into the arrangement. The department of insurance can tell you the fee cap in your state, and a public adjuster asking for more than the cap has told you something useful about how they operate.
The four documents that produce the settlement
The scope of loss comes first: a room-by-room, line-by-line description of what is damaged and what work is required to fix it. Ask for a copy after the inspection, then read it against the house rather than against your feelings about the adjuster. Missing line items are the most common and most fixable problem in a property claim, and they are usually missing because nobody looked behind the baseboard, under the cabinet toe kick, or above the ceiling in the closet. A scope you have reviewed and corrected is worth more than any argument about the total.
The estimate is the scope priced out, typically in software that publishes regional unit costs updated monthly, and it will include overhead, profit and depreciation as separate figures. Get your own contractor's written estimate structured the same way, by line item rather than as a single lump sum, because a lump sum cannot be compared to anything and a line item can. Where the two documents disagree, the disagreement is now specific: a quantity, a unit price, a material grade. Specific disagreements get resolved. General ones get filed.
The proof of loss is the sworn statement of what you are claiming, and it carries a deadline, often sixty days from the carrier's request, that is genuinely binding. Sign it after your inventory and estimates are complete, not before, and if you cannot finish in time, request an extension in writing and keep the reply. The fourth document is the reservation of rights letter, which says the carrier is investigating while preserving its ability to deny later. Receiving one is not a denial. It is notice that a coverage question exists, and it usually names the question, which tells you what to document next.
The file you build, and the habits that keep it usable
Photographs before mitigation, photographs during, and photographs of everything the drying crew removes, all with the camera's date stamp intact. A contents inventory in a spreadsheet with columns for item, room, age, original cost, source of that figure and a photo reference, built room by room while your memory is fresh, because a policyholder's inventory almost always finds more than an adjuster's walkthrough does. Mitigation invoices, moisture readings, and the daily equipment logs from the restoration company. Every receipt for lodging, meals and laundry if additional living expenses are in play, kept separately from the property file.
Then the claim diary, which is the single habit that separates a manageable claim from an exhausting one: a running document with the date, the time, the name and title of who you spoke with, the license or claim handler number, what was said, and what each side agreed to do next. Follow every substantive call with a short email confirming it. You are not building a case for litigation. You are building a record that survives the adjuster's reassignment, the file transfer, the third supervisor, and the eight-week gap in the middle, all of which are ordinary.
Keep it in one place, cloud storage with a folder per category, and name files so the name says what the file is. When a request arrives for the invoice from the plumber who cut the supply line, you want to find it in ten seconds rather than in an evening. Claims that settle cleanly tend to belong to people whose paperwork arrives complete, labeled and on time, because a well-documented file is easy for a carrier to approve and a thin one invites another round of questions.
Verify the license before the first inspection, get the scope in writing after it, and let the estimate comparison carry the argument. That sequence turns a claim from a negotiation about goodwill into a review of documents, which is a much better place for a homeowner to stand.
Further reading
- . Your First Claim, Three Kinds of Adjuster, One Fee. What the Percentage Is Attached To.
- . Drying Fast Looks the Same as Drying Right. The Installer Three Weeks Later Knows the Difference.
- . Keeping a Maintenance Schedule? The Reader You Never Met Decides What It Is Worth.
- . A Split Supply Line Upstairs, and the Four Documents That Run the First Forty-Eight Hours.