Who Pays When the Box Arrives Crushed? Build the Judgment Before You Book
Abstract. Packing choices, liability wording and local delivery rules decide who absorbs a damaged shipment, and most of that is settled before the truck is ever loaded.
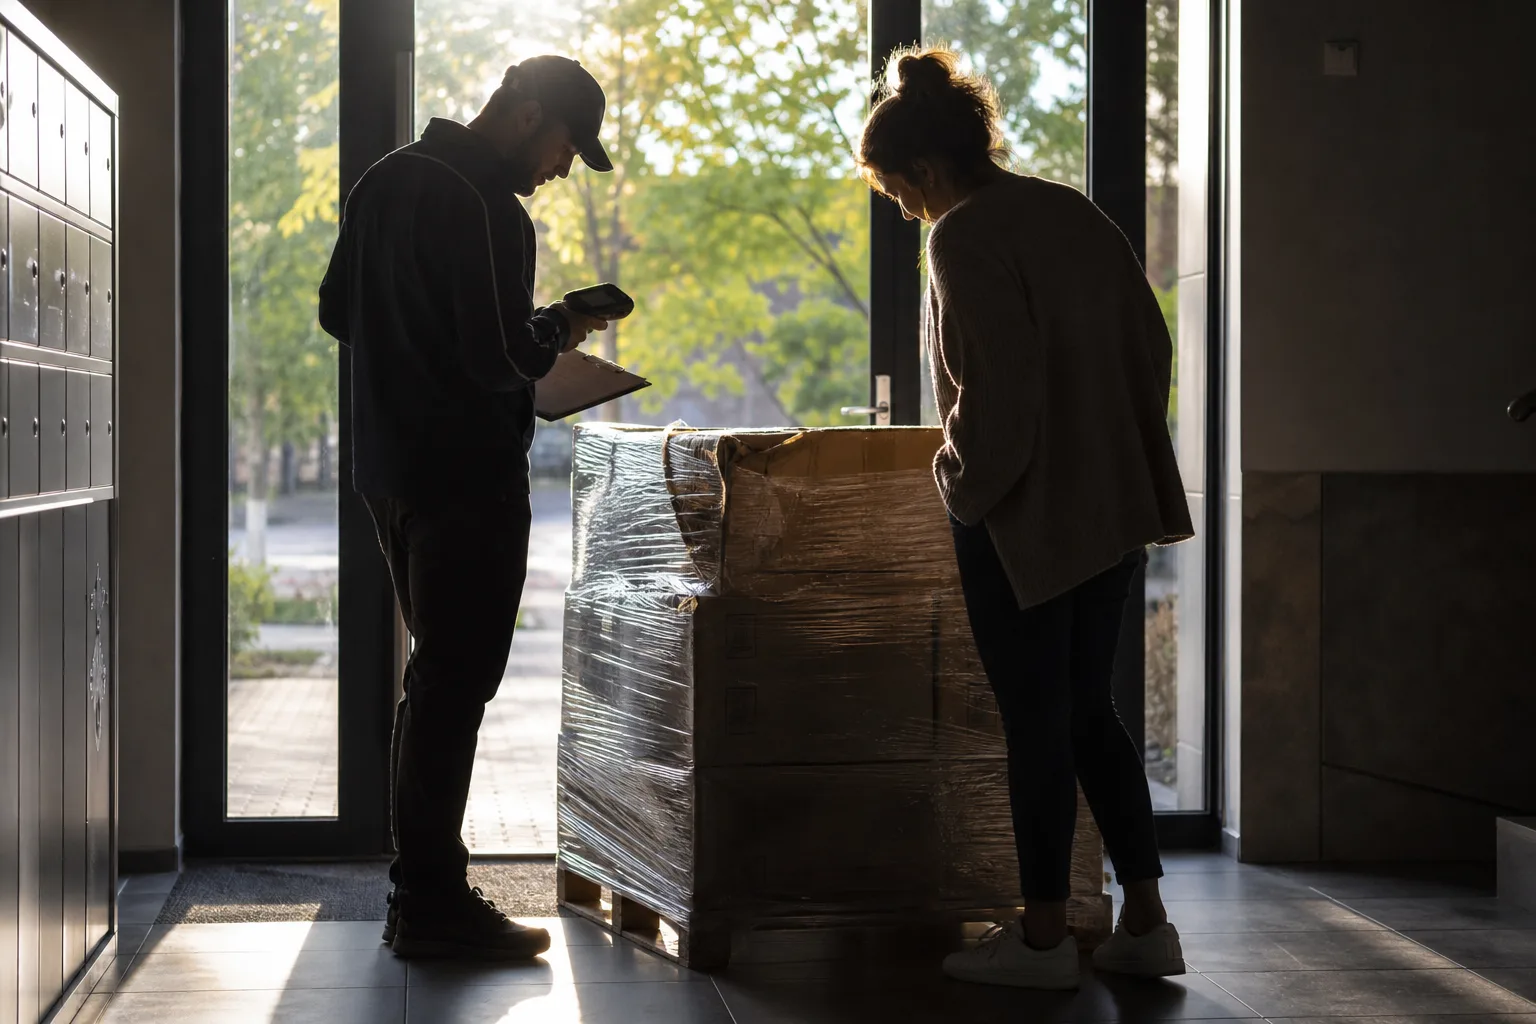
The moment a shipment is damaged, everyone involved reaches for a document written months earlier, and the person who reads that document for the first time at the curb has already lost the argument. Packing, liability wording and delivery class are three separate decisions, made at three separate points, and each one moves the loss toward you or away from you. None of them are hard to understand. They are simply made quickly, by phone, while you are thinking about the price. The judgment worth building is the habit of slowing down at exactly those three points.
Who packs the carton decides more than what goes in it
Carriers draw a hard line between goods they packed and goods they received sealed. When the box is packed by the owner, the carrier's tender usually excludes damage that could be attributed to inadequate internal protection, and the burden of showing the item left your hands intact shifts to you. That is not a trick; it is the only workable rule when nobody watched the packing. The practical consequence is that a self-packed carton with an unlabeled fragile item inside is, for claims purposes, close to uninsured. Paying the carrier to pack the three items you actually care about is often cheaper than the deductible on the argument.
The same logic governs freight. A pallet marked shipper load and count means the driver signed for a wrapped unit, not for the contents, and any concealed damage claim starts from a weaker position. If you cannot lift or stretch-wrap a pallet yourself, this matters twice over, because a poorly built pallet you paid someone else to build is still your pallet under the paperwork. Ask who signs off on the packing, ask whether that signature is recorded on the bill of lading, and keep photographs of the load before the wrap goes on.
Read the liability number, not the word coverage
Most transportation documents promise liability, which is a capped obligation, rather than insurance, which is a separate contract with an insurer. For interstate household goods, the Federal Motor Carrier Safety Administration oversees the framework, and the choice you are given is between released value at a low rate per pound per article and full value protection at a real price. Released value is the default on many order forms, and it is the reason a damaged television produces a check that would not cover the stand. The per-pound structure punishes exactly the goods people care about: light, expensive, hard to replace.
Parcel carriers work differently again, with a declared value that raises the ceiling on a claim without converting the arrangement into insurance, and with published exclusions covering categories such as unpacked furniture, certain electronics and items above a stated value. Freight moves run on tariff-based limits per pound that can be lower still. Before you compare two quotes, convert both to the same question: if this shipment is destroyed entirely, what is the maximum anyone owes me, and who has to prove what to get there. Two prices that look close rarely survive that translation.
The inspection at the door is a physical task, so plan it
Nearly every claims process depends on notations made at delivery, in the moment, on a device the driver is holding. That assumes a consignee who can walk the pallet, crouch to inspect a corner, lift a flap, and stand while the driver waits. If that is not you, the fix is arranged in advance rather than improvised at the curb. Book a delivery window rather than an all-day range, arrange for a second person to be present, and confirm in writing that the driver is expected to wait for inspection. A note that says subject to inspection, damage possible, made before you sign, preserves far more than a phone call the next morning.
Delivery class is the other half of this. Curbside means the pallet stops at the end of the driveway and becomes your problem, including the part where it must be moved before weather reaches it. Threshold delivery brings it inside the first doorway. Room of choice, sometimes with unpacking and debris removal, costs more and eliminates the lifting entirely. For anyone who cannot carry a load or stand and wait, room of choice is not a luxury tier; it is the option that keeps damage from occurring after the carrier's responsibility has already ended.
Local rules change the answer more than most people expect
Interstate moves run on a federal liability framework, but an intrastate move, entirely within one state, is governed by that state's own rules, and those differ substantially in what valuation options must be offered, how estimates bind, and what a carrier must disclose. A move across a metropolitan area that crosses a state line and one that does not can produce different remedies for identical damage. Ask which regime applies to your specific route, and ask it before booking rather than after, because the answer sometimes justifies choosing a different carrier entirely.
Buildings impose their own layer. Many condominium associations and managed apartment buildings require a certificate of insurance naming the association as an additional insured, restrict moves to weekday hours, mandate elevator padding, or require a reserved freight elevator booked days ahead. Some municipalities require a permit to hold curb space for a truck, and in dense neighborhoods a shuttle vehicle may be needed because the trailer cannot legally park within reach of the door. Each of these is a scheduling item that, if missed, turns into a rescheduling fee and a shipment sitting somewhere overnight, which is precisely when the loss becomes ambiguous.
Build the file while the shipment is still moving
A good claim is assembled from material that existed before the damage. Photographs of items before packing, the bill of lading with valuation clearly marked, the delivery receipt with your exception noted, dated photographs of the damage, and a repair or replacement estimate together make a claim that a carrier can pay without a fight. Note the deadlines the moment you book: carriers set a window for filing a written claim and a separate, longer window for bringing suit, and concealed damage typically carries a short window measured in days. Put both dates in a calendar rather than in memory.
The decisions that matter are all made while nothing has gone wrong, which is why they feel optional at the time. Choose the packing party deliberately, price the valuation as a number rather than a reassurance, match the delivery class to what your body can actually do at the door, and confirm which state's rules and which building's rules apply. That sequence costs an hour and settles almost everything worth settling.
Further reading
- . Can't Stand at the Curb to Inspect a Pallet? The Delivery Receipt Decides Who Pays.
- . Can't Lift a Pallet Anymore? Who Actually Handles Your Stock Once a Third Party Stores It.
- . Signing With a Bigger 3PL? Where the Extras Hide in a Fulfillment Quote.
- . Hiring an Outside Specialist? Five Checks That Separate Good From Merely Plausible.