Your Rebuild Cost Moved and Your Limit Didn't. How the Percentage Clause Cuts Your Check
Abstract. Homeowners policies pay partial losses in full only if the dwelling limit tracks rebuild cost; here is how the percentage clause works and which endorsements solve it.
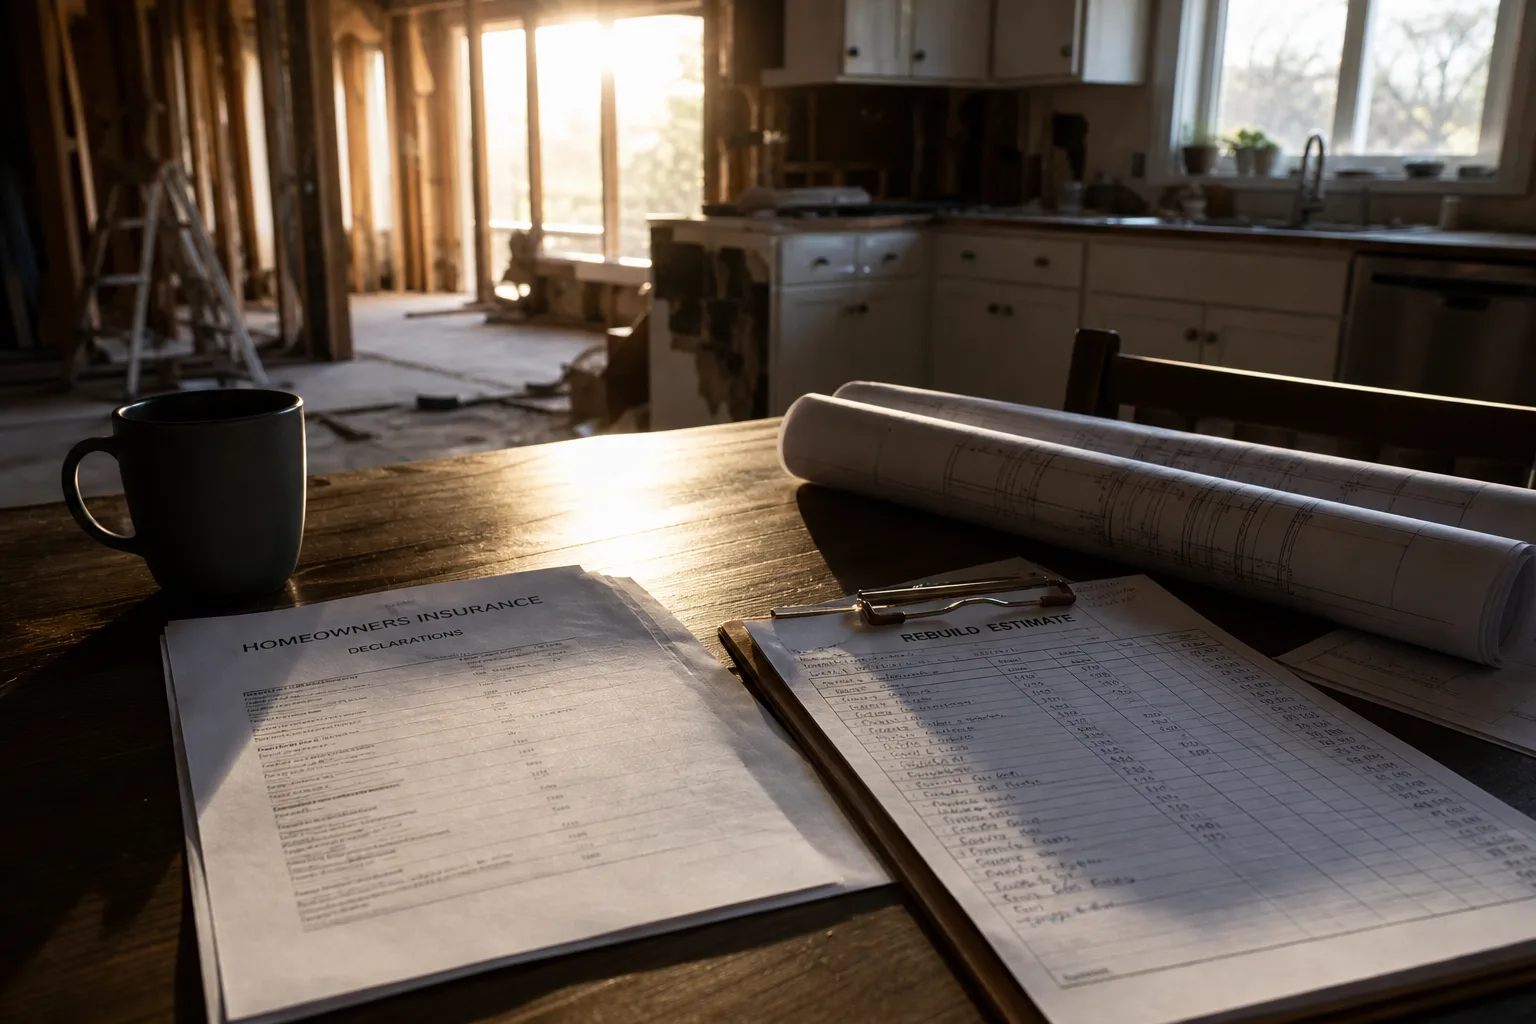
The dwelling limit on a homeowners policy is not what the house sold for, and it is not what the mortgage is. It is an estimate of what a contractor would charge to put the same structure back on the same lot, using whatever materials and labor exist on the day of the loss. That estimate ages badly. When it ages far enough, a clause most policyholders have never read stops paying partial losses in full, and the reduction applies to a kitchen fire just as readily as to a total loss.
The gap opens upstream, months before anyone files a claim
Rebuild cost is a supply-side number, and the supply side moves on its own schedule. Framing lumber reprices on futures. Engineered roof trusses are fabricated to order, and a shop backed up twelve weeks prices differently than a shop with open capacity. Windows in a nonstandard size get quoted with a lead time attached, and a lead time is money, because the general contractor carries the site, the dumpster, and the temporary protection until the unit arrives. None of that shows on a renewal notice. The limit on the declarations page was set in a market that no longer exists.
Substitution compounds it. When the specified product is unavailable, the estimator prices whatever can be delivered, which is frequently the better-stocked item rather than the cheaper one. A household that finished a basement, replaced a roof, or added a bathroom has moved its own number too, and insurers generally do not learn about permitted work unless someone tells them. So the exposure grows from two directions at once, market pricing above and improvements below, while the coverage figure sits still.
What the percentage clause actually does to a partial loss
Most homeowners forms condition full replacement cost payment on carrying a limit equal to some percentage of the current rebuild cost, commonly eighty percent. Meet it and a partial loss is settled at replacement cost, subject to the deductible. Fall below it and the settlement is reduced in proportion. The arithmetic is unforgiving: if the clause requires eighty percent and you carry three quarters of that requirement, the insurer owes roughly three quarters of the repair cost, and you fund the rest. Commercial policies call this coinsurance, and property professionals often call the reduction averaging. The name changes; the multiplication does not.
Two features of the clause surprise people. First, it bites hardest on ordinary claims, because a total loss is capped at the limit anyway, while a sixty thousand dollar fire gets scaled down by a formula. Second, the test is applied at the time of loss, using the rebuild cost then, not the one calculated at the last inspection. A quiet year of material escalation can move a household from compliant to short without a single change to the policy or the house.
The endorsements that exist to close the gap
The protections are standard products, not exotic ones, and they are priced as small percentages of premium. Inflation guard adjusts the dwelling limit automatically at each renewal by an index, which keeps the number from drifting quite so far. Extended replacement cost adds a cushion above the stated limit, often expressed as an additional twenty five or fifty percent, and it is the single most useful purchase in a market with volatile material pricing. Guaranteed replacement cost, where an insurer still offers it, removes the ceiling entirely for the covered structure, though eligibility rules are strict and the underwriting inspection is real.
Ordinance or law coverage is the one households skip and later need. It pays the extra cost of rebuilding to current code, which is where a 1962 house with knob-and-tube remnants, no hurricane clips, and a nonconforming stair run becomes expensive. Personal property has its own version of the problem, since the contents limit is usually a percentage of the dwelling limit and jewelry, firearms, and instruments sit under sublimits that a scheduled endorsement lifts. Flood is separate entirely, written through the National Flood Insurance Program, which the Federal Emergency Management Agency administers, and its dwelling coverage stops at a statutory cap that excess flood policies are designed to sit above.
How a household checks its own number
Ask the carrier for the reconstruction cost worksheet behind your dwelling limit, in writing. It exists, it lists square footage, exterior finish, roof type, foundation, and interior grade, and it is frequently wrong in ways you can see immediately: a finished basement counted as unfinished, two full baths recorded as one, tile recorded as vinyl. Correcting those inputs is free and it is the highest-yield thing you will do all year. Where the house is unusual, older, custom, stone, or timber, a local general contractor will price a hypothetical rebuild for a modest fee, and that estimate carries weight in a coverage conversation.
Then keep the file current. Permits, invoices, and dated photographs of completed work establish both the existence and the quality of improvements, and they answer the question an adjuster will otherwise have to guess at. State insurance departments regulate the forms and license the agents, so a written request for an increased limit or an added endorsement produces a documented record of when you asked. Renewal is the natural moment, but a mid-term endorsement takes a phone call and takes effect the day it is issued.
The clause is not hidden and it is not unusual. It is a condition of the discount you already receive for insuring to value, and it can be satisfied with a corrected worksheet, an extended replacement cost endorsement, and a note to the agent after the next permitted project.
Further reading
- . Filing a Claim Without Hurting Next Year's Renewal? Compare the Four Routes First.
- . First Commercial Policy? How the Coinsurance Clause Decides What a Partial Loss Pays.
- . First Claim on the Policy? Three Routes to the Same Repair, and What Each Puts on Your Record.
- . Backordered Siding, a Long Repair, and the Exclusion That Decides Who Pays for the Wait.