Filing a Claim Without Hurting Next Year's Renewal? Compare the Four Routes First
Abstract. Four ways to report damage to a homeowners insurer, what each one leaves in your permanent claim record, and the paperwork that keeps the next renewal quiet.
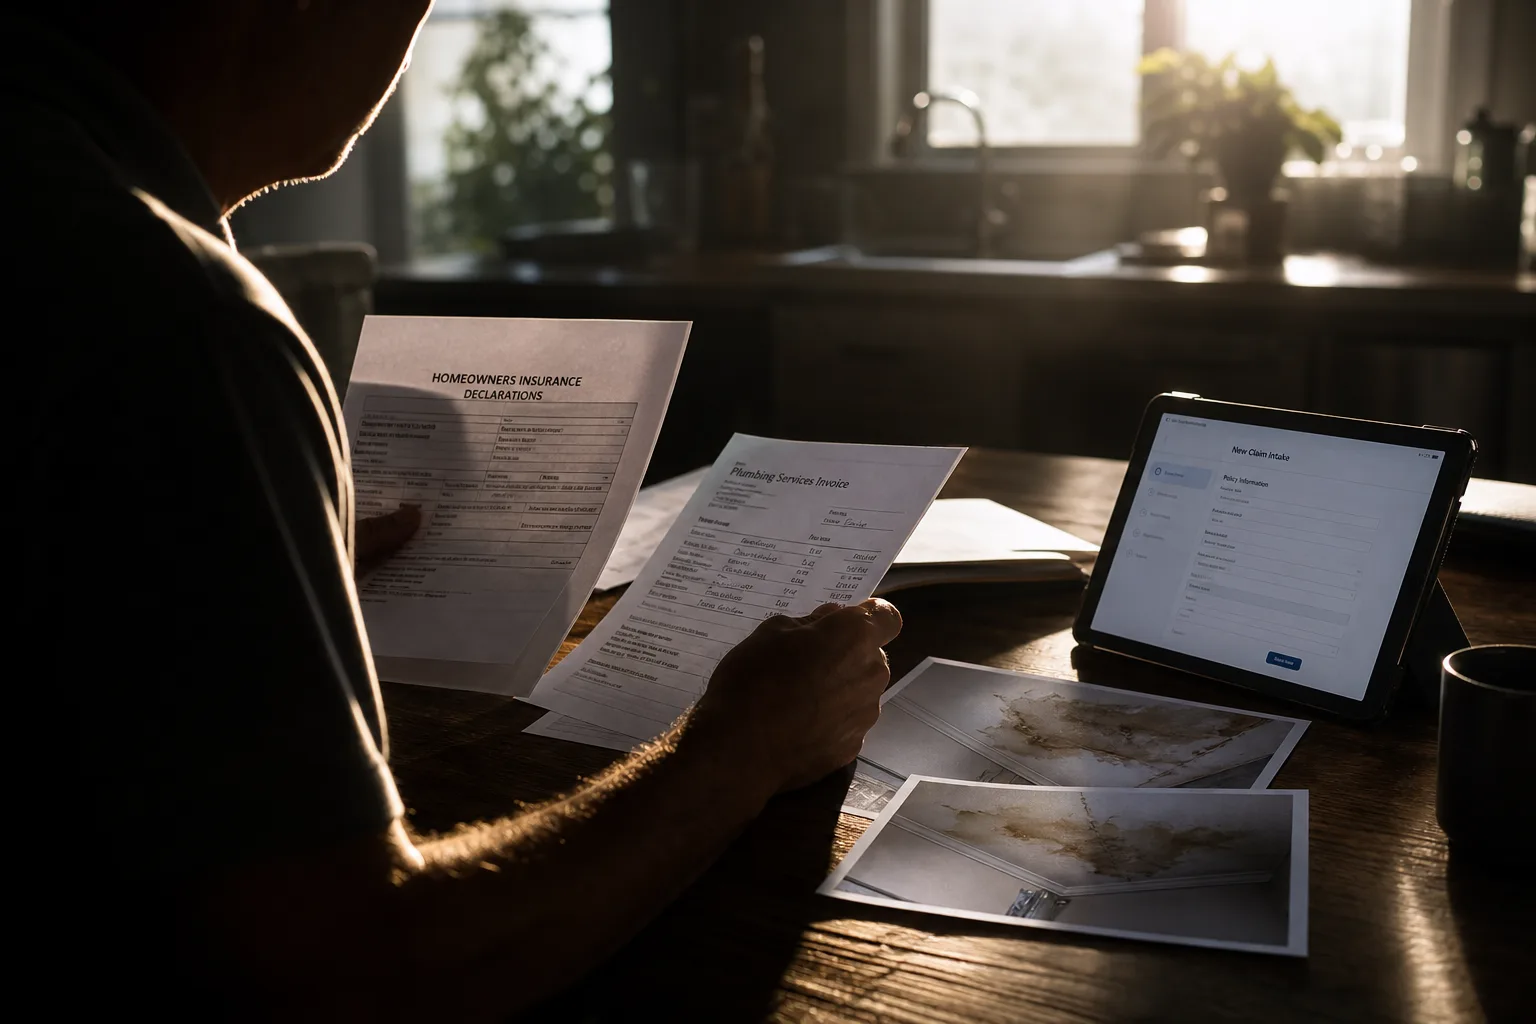
The decision most people get wrong happens before any claim exists. You call the insurer, describe the ceiling stain, ask whether it would be covered, and hang up without filing anything. Months later a renewal arrives with a loss-free discount missing, and the explanation is that a contact was logged. That contact is now visible to the next carrier you shop. Understanding which of the available routes creates a record, which creates a claim, and which creates a paid claim is the difference between one bad month and three bad renewals.
The inquiry, the notice of loss, and the paid claim are three different things
An inquiry is a question. A notice of loss opens a file with a claim number and an assigned adjuster. A paid claim closes with money leaving the insurer. All three can appear in your loss history, and that is the part that surprises people who assumed nothing counts until a check clears. Insurers report to shared claim databases, and the resulting report follows the property and the named insured for several years. The Federal Trade Commission oversees how consumer reports of this kind may be used and disputed, which is why you are entitled to see yours.
What changed recently is the sensitivity of the pricing that sits on top of that history. Carriers have narrowed their appetite in states with heavy weather and water losses, and the tools they use to sort applicants now weigh claim frequency more heavily than claim size. Two small water claims can read worse than one large fire. So the practical question stopped being whether a loss is covered and became whether the loss is large enough to justify entering the record at all. That calculation deserves the deductible in front of you, in writing, before the call.
Route one, the app: fastest documentation, least explanation
Every major carrier now runs photo-first intake through a phone app. You upload dated images, tag a room, and the file opens without a conversation. For anyone who cannot hold a phone overhead, stand on a stool, or wait forty minutes on hold in a hallway with no chair, this is the gentlest route physically. It is also the least forgiving in one respect: the upload commits you. There is no version where you ask a clarifying question and then decline to proceed, because the submission itself is the notice of loss.
Use it when you already know the damage exceeds your deductible by a comfortable margin and you want the timeline started while conditions are still visible. Photograph from a seated position with a wide lens rather than climbing for a close-up; adjusters accept context shots and will send someone for the height. Keep the same images in your own folder with original file dates intact. Apps compress and strip metadata, and the copy on your own drive is the one that settles arguments about when the stain appeared.
Route two, the coverage question that leaves no trace
If what you actually need is an interpretation of your policy rather than a payment, ask someone who does not report to a claim database. Your own declarations page and the policy form answer more than people expect, particularly on water damage, where the distinction between a sudden discharge and long-term seepage decides the outcome. An independent agent, a public adjuster on a paid consultation, or an attorney who reviews the form for a flat hour will read the exclusions with you. None of them opens a file.
This is the route that changed most. Written policy forms and endorsements are now routinely available as downloadable documents in the customer portal rather than mailed once and lost, so a reader who cannot get to a filing cabinet in a basement can pull the exact language on a tablet. Print the declarations page, the endorsement list, and the water and wear-and-tear exclusions. Those four items answer the majority of borderline questions, and having them in hand converts a vague phone call into a specific one you may not need to make.
Route three and four: the assisted claim and the contractor-run claim
The assisted claim is the traditional one. You call, an adjuster is assigned, and an inspection follows. What is different now is that the inspection may never involve a person on your roof. Virtual adjusting, video calls, and aerial imagery flown by drone or ordered from an existing photo library have become normal, which removes the old requirement that somebody in the household escort a stranger up a ladder or through a crawlspace. If your mobility makes the walkthrough hard, say so at intake and ask for the remote option by name; carriers have it and rarely offer it first.
The contractor-run claim is where a restoration company handles the paperwork, sometimes under an assignment of benefits that transfers your rights to payment. It is genuinely useful when water is still spreading and nobody in the house can move furniture or run fans. It also moves control, and several states have tightened what those assignments may contain after disputes over inflated invoices. If you sign one, cap the scope, keep the right to approve the estimate, and understand that the claim remains yours in the record even when the money goes to the contractor.
The folder that protects the renewal
Whichever route you take, the same small set of documents does the work: the declarations page for the year of the loss, dated photographs before and after, the plumber's or roofer's written diagnosis naming a sudden cause, receipts for the emergency mitigation, and the adjuster's estimate with the line items visible. Add one more that people forget. If you open a file and then decide not to pursue it, request written confirmation that the claim was closed without payment, and ask how it will be coded. That single email is what you show the next underwriter who asks.
Order your loss history report once a year, the way you would a credit report, and read it against your own folder. Errors on these reports are correctable, and a claim listed under the wrong cause or the wrong amount is worth disputing before you shop coverage rather than during. The quiet renewal is the one where you already know what the carrier sees.
Further reading
- . First Commercial Policy? How the Coinsurance Clause Decides What a Partial Loss Pays.
- . First Claim on the Policy? Three Routes to the Same Repair, and What Each Puts on Your Record.
- . Your Rebuild Cost Moved and Your Limit Didn't. How the Percentage Clause Cuts Your Check.
- . Backordered Siding, a Long Repair, and the Exclusion That Decides Who Pays for the Wait.