Complaining to a Company Too Big to Call Back? The Order That Still Works
Abstract. How escalating a complaint against a large provider changed in a decade, and the order that still gets a decision from someone who can authorize one.
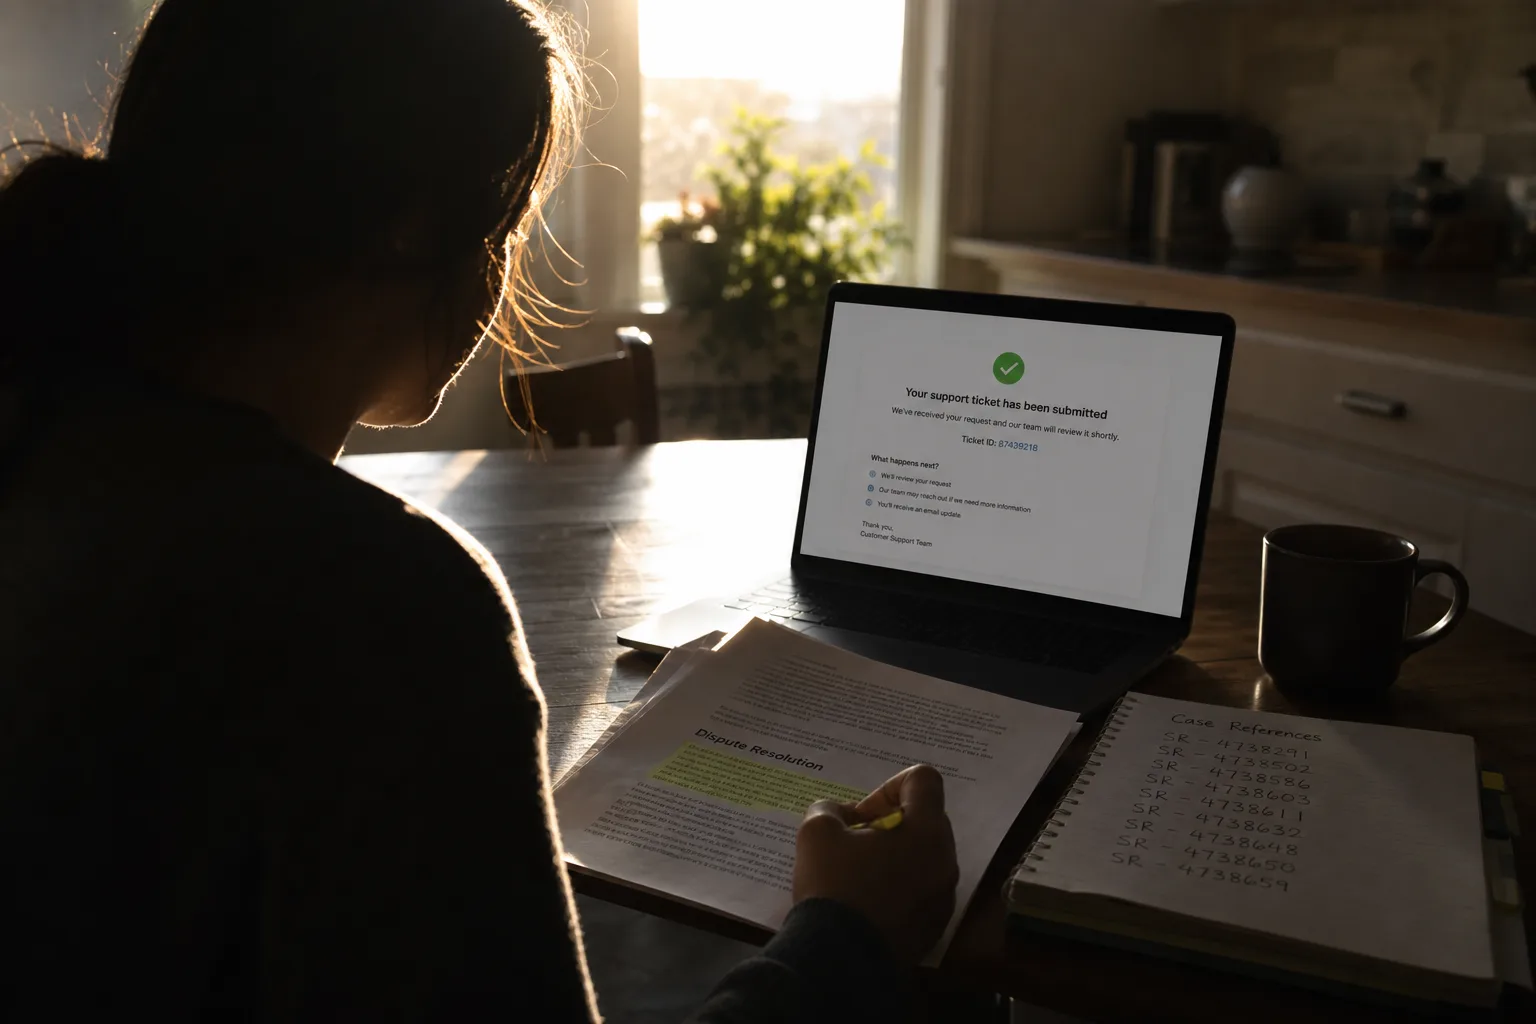
The first person who answers is almost never the person who can pay you. That was true a decade ago and it is true now, but the route between that person and the one holding the budget has been rebuilt, and the rebuild mostly favors you. Ten years ago escalation meant a phone tree, a supervisor with real discretion, and a paper letter to a head office address printed in six-point type on the back of a statement. Now it means a case number, a transcript you can request, a written contract clause that dictates the sequence, and a regulator with an intake portal that runs on a clock.
The first tier has less room to decide and leaves a much better trail
Front-line agents at large providers work inside narrower authority than their predecessors did. Refund bands are set centrally, goodwill credits are capped by system rules rather than judgment, and the person on the line often cannot see the underwriting or billing logic that produced the outcome you are disputing. That sounds like a loss, and in the moment it is. What replaced the discretion is a record: a ticket number, a timestamped transcript, a disposition code, and in many cases an email confirmation sent automatically. Ten years ago you took notes on the back of an envelope and hoped the call was among the ones being recorded for quality purposes.
Use the first contact to build that record rather than to win. Ask for the case or reference number before you explain anything, ask whether a transcript can be emailed to you, and ask one specific question: what is the highest amount or the widest remedy this department is authorized to approve. A capped agent will usually tell you, because the cap is not a secret. When the answer falls short of what you are asking for, you have established, in writing, that the first tier cannot resolve it, which is exactly the finding the second tier needs before it will open a file.
Get the name, then check what the name is actually licensed to do
Job titles inside large organizations are internal inventions. Customer advocate, resolution specialist, escalations manager and client experience lead are all real roles, and none of them is vetted by anyone outside the company. That is not a criticism; it matters only because people assume a grand title implies an outside credential, and sometimes it genuinely does. An insurance claim handler making coverage decisions is often a licensed adjuster, and adjuster licenses are searchable through the state department of insurance. A mortgage servicer's loss mitigation staff and the loan officers behind the original file carry NMLS identification numbers you can look up yourself through the public consumer access database. Ask for the number, not the title.
The same check applies to the word ombudsman, which large companies now use for internal review offices. An internal ombudsman can be genuinely useful and often has authority the second tier lacks, but the office reports to the company, and calling it an ombudsman does not put an independent body between you and the provider. Ask who the office reports to and whether its decision binds the company. A straight answer to that question tells you whether this rung is a real appeal or a well-staffed second opinion, and either way you now know what you are climbing toward.
Find the clause that sets the order before you choose the next rung
The single biggest change in ten years sits in the contract rather than the call center. Arbitration provisions with class action waivers are now standard in consumer agreements across banking, telecommunications, home warranties and retail credit, and most of them include a step you skip at your cost: a written notice of dispute, sent to a named address, starting a waiting period of thirty or sixty days before either side can file anything. Many of the same clauses carve out small claims court explicitly. Read the dispute resolution section before you send the first formal letter, because it tells you the order the company has already agreed to follow, and it usually gives you a mailing address that reaches a legal department rather than a queue.
Send that notice even if you expect nothing from it. It is cheap, it is dated, and it converts a scattered set of phone calls into a formal claim with a defined response window. It also changes who reads your file. A notice of dispute delivered to the address named in the contract lands with people whose job is to price risk, not to manage call volume, and those people settle things the front line was never authorized to settle.
The outside step is a portal now, and portals run on deadlines
Regulatory complaints used to be letters that vanished into a file room. Most are now web intakes with tracking numbers, and several route the complaint straight to the company with a response deadline attached. The Consumer Financial Protection Bureau maintains the complaint process for consumer financial products and services, and state insurance departments, state attorney general consumer protection divisions and the Federal Communications Commission run comparable intakes for their sectors. Choose one whose remit actually covers your provider, describe the sequence you followed rather than your frustration, and attach the case numbers you collected at the first tier. Specificity is what makes a file answerable.
Filing with a regulator is not a substitute for the contractual notice, and running both is normal. What it adds is a second party watching the clock, which changes how quickly an internal review office schedules your file. It also creates a record outside the company's own systems, and that record survives staff turnover, acquisitions and the retirement of whatever ticketing platform held your transcript.
Escalation works when each step produces something the next step needs: a number, a name, a written refusal, a dated notice. Ten years ago you had to build most of that yourself. The provider now builds a good deal of it for you, and the reader who asks for it in the right order at the right moment ends up in front of someone who can sign.
Further reading
- . Asked Your Landlord for a Ramp and Been Refused? What the Legal Quote Actually Covers.
- . Winter Damage, Thin Proof? The Dated Records Someone Else Is Already Keeping for You.
- . Quoted an Hourly Rate? What That Number Is Attached To, Week by Week.
- . Quoted a Flat Fee for Legal Work? What That Number Is Actually Measured Against.